Market Overview and Scope of the Drone Navigation System Market
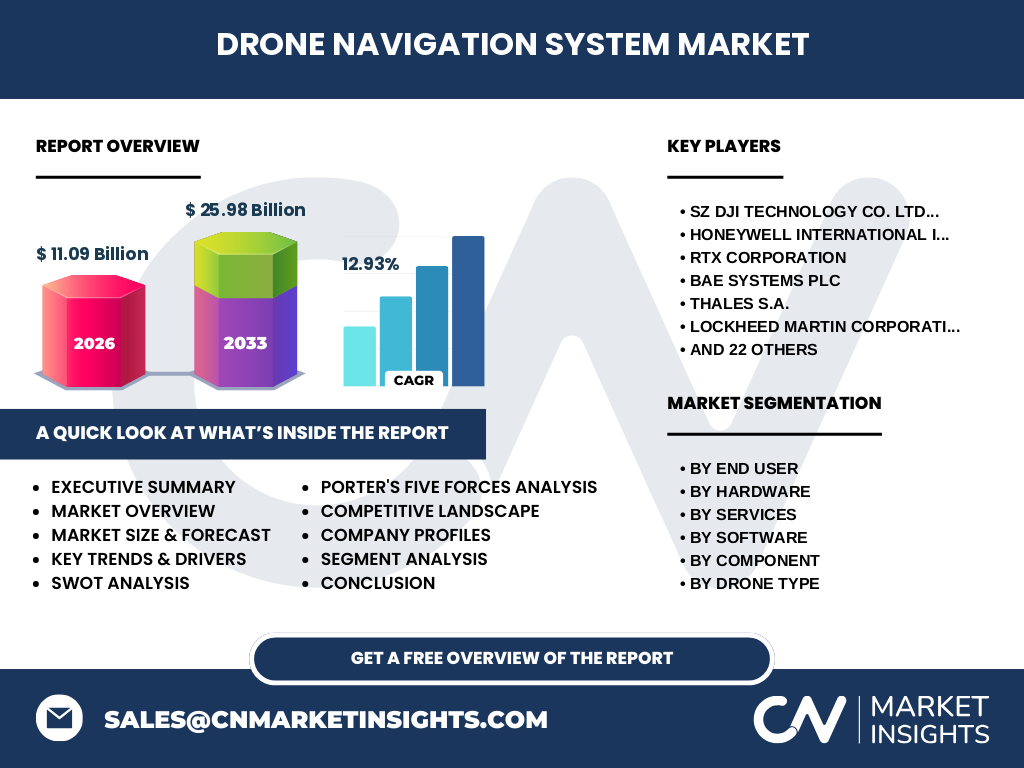
Our analysis indicates the Drone Navigation System Market is valued at 11.09 Billion in 2026, encompassing critical flight controllers, positioning modules, and vision-based navigation hardware. This sector facilitates autonomous flight across defense and commercial infrastructure. Industry participants like SZ DJI Technology Co. Ltd. and Honeywell International Inc. drive mission-critical operational precision.
Structural Growth Drivers and Market Restraints
The market thrives on surging demand for autonomous logistics, yet faces severe regulatory hurdles from the FAA and EASA regarding BVLOS operations. Supply chain constraints for rare-earth metals used in inertial sensors create bottlenecks. Companies like RTX Corporation and BAE Systems plc leverage advanced jamming-resistant technologies to mitigate these operational roadblocks successfully.
The Shift Toward Hybrid and Vision-Based Navigation
Industry trends reveal a rapid transition from standalone GPS to hybrid navigation systems and vision-based architectures. This evolution guarantees operational continuity in GNSS-denied environments. Firms such as SBG Systems S.A.S. and Auterion AG are leading this technical shift, empowering industrial users with unmatched positioning accuracy during complex survey missions.
COVID-19 Impact Analysis and Post-Pandemic Recovery
The pandemic initially disrupted semiconductor supply chains for flight controllers and communication systems, halting production lines globally. However, our research confirms a robust recovery trajectory driven by contactless drone deliveries and remote monitoring software adoption. Aerospace pioneers like Lockheed Martin Corporation and Northrop Grumman Corporation rapidly pivoted supply chains to stabilize regional distribution networks.
Competitive Benchmarking in the Drone Navigation Market
Market concentration remains moderately high, with defense primes and specialized avionics manufacturers dominating ecosystem supply chains. Strategic positioning dictates that giants like Thales S.A. and L3Harris Technologies Inc. capture high-value government contracts, while agile innovators like Skydio Inc. and Parrot Drones SAS capture lucrative commercial enterprise shares through advanced obstacle avoidance software.
Executive Summary of the Drone Navigation System Market
Driven by a robust 12.93% CAGR, the Drone Navigation System Market will surge from 11.09 Billion in 2026 to 25.98 Billion by 2033. Our comprehensive research highlights autonomous navigation software and hybrid sensor fusion as primary catalysts. Defense organizations and industrial users represent the vanguard of this unprecedented multi-billion-dollar market expansion.
Long-Term Market Forecast from 2027 to 2033
Projected data dictates that market valuation will expand aggressively through the forecast window, achieving 25.98 Billion by 2033. This trajectory stems from commercial scalability in urban air mobility and strict industrial compliance mandates. Technology developers like Swift Navigation Inc. and Topcon Positioning Systems are strategically positioned to capitalize on this decade-long valuation surge.
Segmentation Analysis Across Hardware, Software, and Services
Our research segments the ecosystem into hardware, software, and services, alongside specific drone types like fixed wing drones and rotary wing drones. Hardware components dominate baseline revenues, while autonomous navigation software and managed drone services exhibit the fastest acceleration. End users span defense organizations, commercial enterprises, government agencies, and industrial users.
Regional Market Distribution and Global Performance
Geographic distribution reveals North America and Europe leading adoption due to mature aerospace frameworks governed by strict aviation authorities. Meanwhile, the Asia-Pacific region demonstrates the highest growth velocity, fueled by manufacturing hubs in India and China. Localized infrastructure investments by firms like Garuda Aerospace Private Limited and ideaForge Technology Limited accelerate regional deployment.
In-Depth Regional Review of High-Growth Geographies
North America retains dominance through heavy defense spending managed by RTX Corporation and General Atomics Aeronautical Systems. Conversely, the Asia-Pacific theater prioritizes commercial agricultural mapping and industrial inspection. Regulatory harmonization by regional civil aviation bodies continues to unlock previously restricted airspace for commercial enterprises across both territories.
Strategic Positioning of Leading Company Profiles
Industry leaders maintain competitive moats through proprietary sensor integration and robust patent portfolios. Entities such as Trimble Inc., Hexagon AB, and Garmin Ltd. focus on high-precision GPS positioning modules. Meanwhile, defense-centric innovators like AeroVironment Inc. and Embention (Veronte) prioritize failsafe flight management software for tactical military applications.
Porter's Five Forces Analysis of Competitive Pressures
The threat of new entrants remains moderate due to steep R&D expenditures required for certified navigation sensors. Bargaining power of suppliers is high for specialized optical cameras and tactical-grade IMUs. Competitive rivalry is intense, forcing firms like Teledyne FLIR and UAV Navigation-Grupo Oesía S.L. to continuously innovate their path planning software.
SWOT Analysis of the Drone Navigation Ecosystem
Strengths lie in high-accuracy hybrid sensor fusion and growing autonomous capabilities. Weaknesses involve vulnerability to electronic jamming. Opportunities abound in urban logistics integration, whereas threats encompass tightening cybersecurity regulations. Companies like Asteria Aerospace Limited and Zen Technologies Limited continually adapt their software architecture to mitigate these specific operational risks.
Value Chain Analysis from Raw Materials to End-Users
The value chain originates with raw material providers supplying silicon wafers and rare-earth magnets for inertial sensors. Mid-stream manufacturers fabricate hardware components and software algorithms. Downstream integration involves system integrators and managed service providers delivering turnkey solutions to end-users like defense organizations and commercial infrastructure inspection agencies.
Investment Insights and High-Potential Growth Areas
Investors should direct capital toward autonomous navigation software and GNSS-independent vision systems. These niches promise superior margin expansion as regulatory frameworks evolve. High-potential plays include agile firms like Emlid Tech Kft., Paras Aerospace Private Limited, and SBG Systems S.A.S., which offer scalable software update services and robust technical support.
Conclusion and Strategic Takeaways for Stakeholders
The Drone Navigation System Market represents a transformative technology sector scaling toward 25.98 Billion by 2033. Stakeholders must prioritize investment in resilient, jam-proof navigation technologies and modular software suites. Capitalizing on defense and commercial demand will separate market leaders from legacy laggards in this high-growth ecosystem.
Research Methodology and Baseline Estimation Techniques
Our methodology triangulates primary stakeholder interviews with aerospace executives, trade registry datasets, and secondary macroeconomic indicators. Baseline estimates for 2026 are cross-referenced with shipment data of flight controllers and positioning modules. This rigorous validation guarantees high-fidelity market sizing and accurate CAGR projections.
Scope of the Report and Analytical Parameters
This report covers global revenue performance across hardware, software, and service segments from 2027 to 2033. Geographic scope encompasses North America, Europe, Asia-Pacific, Latin America, and the Middle East. Analytical limitations exclude unverified consumer-grade hobbyist drone expenditures, focusing strictly on professional enterprise and military-grade navigation systems.
Recent Developments, Partnerships, and Strategic Moves
Recent industry momentum features strategic mergers, joint defense contracts, and advanced product launches in vision-based navigation. Key market participants frequently partner with avionics institutions to upgrade obstacle avoidance software. These proactive corporate maneuvers reinforce competitive advantages and accelerate commercial time-to-market for next-generation hybrid navigation systems.